
GBP to INR Converter + Budget Planner
Convert pounds to rupees, subtract the transfer fee and set a monthly amount to send to India after UK rent, council tax and bills. Rates are indicative; check the live rate before you send.
Use the calculator➜ Try EMOH Pay free➜
How do I budget in GBP and INR?
To budget in GBP and INR, cover UK rent, council tax, energy and transport in pounds first, then set a fixed monthly pound amount for India, such as 10% to 15% of take-home pay. Convert it to rupees after fees and exchange margin, agree the rupee figure with family, and keep a small buffer in pounds for rate changes.
Your UK costs come first. Most UK salaries are paid monthly, and rent, council tax and energy bills leave your account early in the month. Set the GBP to INR transfer as a fixed bill right after them, then spend what remains.
The calculator above covers the maths. Amount in GBP is the transfer. Transfer fee (%) is the provider's charge; divide a flat fee by the amount to get a percentage. Share of your GBP income to send home and monthly income in GBP are optional and show the monthly figure in both currencies.
See the EMOH Pay features page for how multi-currency tracking works, and our currency converter for other pairs. Sending from the US too? Try the USD to INR converter.
GBP to INR today: why providers quote less than the headline rate
The GBP to INR rate shown in search results is the mid-market rate. Banks and transfer services add an exchange margin, and some add a fee. A high street bank transfer can cost several percent in total, while specialist providers are often cheaper for regular amounts.
The fair test is rupees received for the same number of pounds. The rate in this tool is an indicative 2026 figure for planning, so check a live GBP to INR rate and your provider's quote on the day.
| Scenario | Fee | Exchange margin | Rupees received |
|---|---|---|---|
| Mid-market, no costs | £0 | 0% | ₹55,000 |
| Specialist provider | £1.50 | 0.4% | ₹54,616 |
| "No fee" offer | £0 | 1.5% | ₹54,175 |
| Bank transfer with higher costs | £15 | 3% | ₹51,750 |
The best and worst options differ by about ₹2,900 on a £500 transfer, or roughly ₹34,000 over a year of monthly transfers. Our guide to remittance fees explained shows how to compare total cost.
Sending money from the UK to India safely
- Check the FCA register. UK money transfer firms should be authorised or registered with the Financial Conduct Authority. The FCA's online register lets you confirm a firm before you send.
- Choose the right account in India. Non-resident Indians usually send foreign earnings to an NRE account, which is repatriable and pays interest that is tax-free in India. NRO accounts hold income earned in India, and their interest is taxable there.
- Keep records. Transfer confirmations help if you later move money back, buy property in India or need to show where funds came from.
- Tax on both sides. Money you send to family is not an expense for UK tax. UK residents may need to declare income or gains from Indian accounts; a cross-border adviser can confirm what applies.
Sample budget: a UK salary with money sent to India
This example assumes a single person outside London with £2,600 a month in take-home pay who sends £300 to India. It is illustrative, not a statistic. London rents would push the housing line much higher.
| Category | GBP per month | Notes |
|---|---|---|
| Rent | £950 | One-bedroom flat or a room in London |
| Council tax | £130 | Depends on band and council |
| Energy | £120 | Higher in winter |
| Water | £40 | Regional supplier |
| Broadband and phone | £50 | SIM-only plan plus fibre |
| Groceries | £280 | Mostly home cooking |
| Transport | £150 | Bus or rail pass |
| Money sent to India | £300 | About ₹32,700 after costs |
| Savings and emergency fund | £300 | Three months of costs first |
| Dining and personal | £200 | Flexible |
| Buffer | £80 | Rate moves and surprises |
For UK living costs in more detail, see the cost of living in London or the budgeting app for the UK page. For the family receiving the money, the monthly budget planner for India splits rupee income into needs, wants and savings.
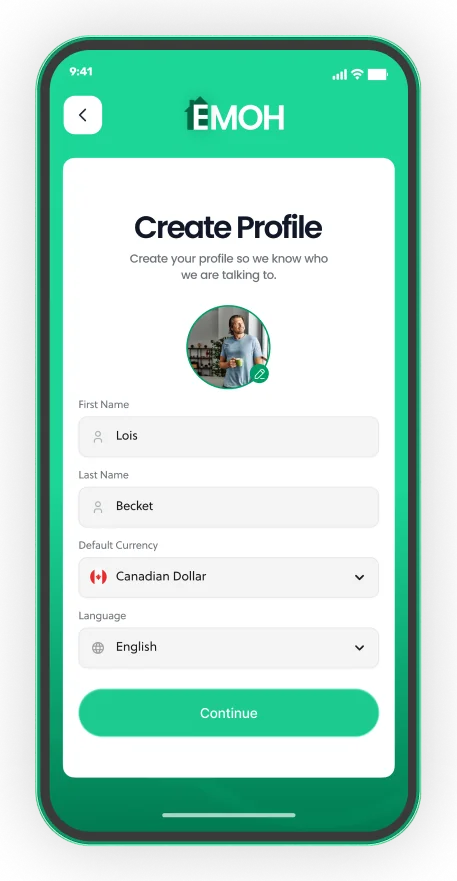
Your home currency, any spending currency
- 148 currencies with automatic conversion
- Record FX markup on card purchases
- Phone and web always in sync


Money going the other way: parents funding a student in the UK
Many Indian families send rupees to children studying in the UK. Under the Reserve Bank of India's Liberalised Remittance Scheme, resident individuals can send up to US$250,000 abroad per financial year for permitted purposes, including education. Tax collected at source can apply above a threshold, so check with your bank before large transfers.
On the UK side, students should budget in pounds from the first month. Our study abroad budget calculator turns tuition, rent and living costs into a yearly total and a monthly figure.
Tips for a steady GBP to INR plan
- Send on a fixed day after payday, once rent and council tax have left your account.
- Agree a rupee target with family and adjust the pound amount only when the rate moves noticeably.
- Compare rupees delivered across two or three FCA-regulated providers for your usual amount.
- Plan ahead for Diwali, weddings and tuition fees so large transfers are not rushed.
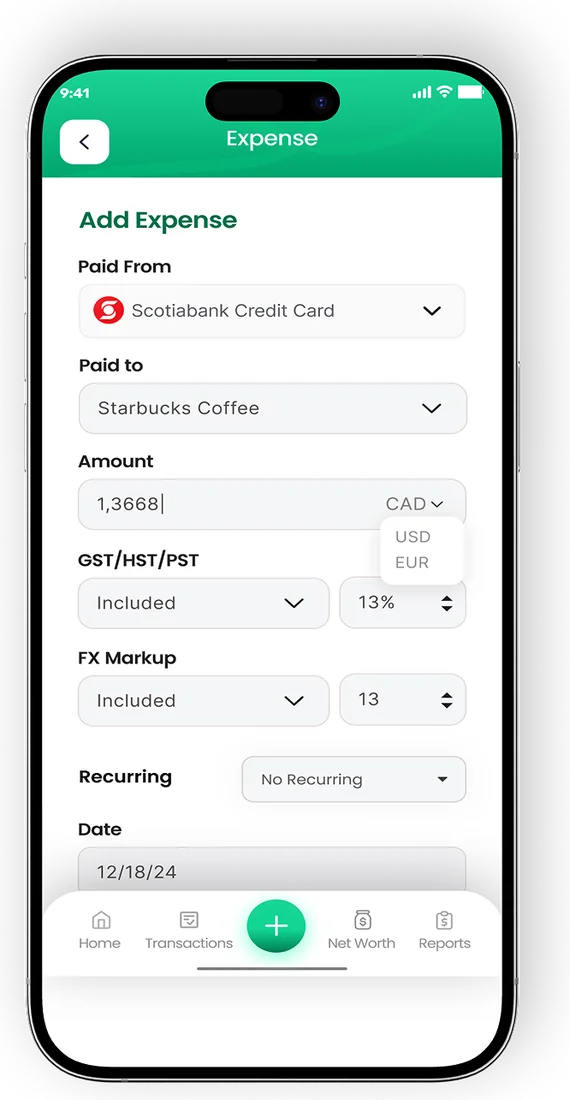
- Track each transfer in EMOH Pay. It is free on iPhone, Android and the web and converts across 148 currencies automatically, so pounds sent and rupees received sit side by side.
Every currency in one app


Put the numbers on autopilot
EMOH Pay tracks your spending, budgets and net worth on your phone and in the browser, always in sync. Free to start, made in Canada.
Get started free➜GBP to INR Converter + Budget Planner: frequently asked questions
Is the GBP to INR rate in this calculator live?
No. It uses an indicative 2026 rate for planning. Check a live rate and your provider's quote before you send.
What is the cheapest way to send money from the UK to India?
Compare rupees received for the same pound amount across FCA-regulated providers. Specialist transfer services are often cheaper than high street bank transfers, but quotes change daily.
Should I send money to an NRE or NRO account?
Foreign earnings usually go to an NRE account, which is repatriable and earns interest that is tax-free in India. NRO accounts are for income earned in India. Check with your bank.
How much should I send to India each month?
There is no official rule. Many people choose 10% to 15% of take-home pay, but only after UK essentials and their own emergency fund are covered.
Can my family in India share the budget?
Yes. EMOH Pay's family sharing gives each person their own login to one shared budget, with amounts shown in rupees or pounds.
Sources and further reading
Related guides and tools
Quick conversion between major currencies (indicative 2026 rates — live rates inside the EMOH Pay app, with 148 currencies…
USD to INR Converter + Budget PlannerConvert USD to INR, see what fees and exchange margins cost in rupees and plan how much of your US salary to send to India…
Budgeting App for United KingdomEMOH Pay works in United Kingdom: budget in GBP plus 147 other currencies, on your phone and the web. Track spending in…
Budgeting App for IndiaEMOH Pay works in India: budget in INR plus 147 other currencies, on your phone and the web. Budget in rupees with full…
Cost of Living in London (2026)Cost of living in London for 2026: typical rent, council tax, TfL fares, energy bills and sample monthly budgets for a…
Remittance Fees ExplainedRemittance fees explained simply: upfront fees, exchange margins and receiving charges, with a worked example and the…
Start free today
Free on iPhone, Android and the web. Upgrade to EMOH Pro anytime for bank sync and advanced AI.
Download for iOS➜ Get it on Android➜