Saving For Our Dream House Sounded Stressful. Then We Found EMOH Pay
Saving for our dream house felt overwhelming at first. Every time we looked at home prices, calculated a down payment, or thought about closing costs, the number felt bigger than our motivation.
And that is exactly why most people delay the process.
The problem is not income. The problem is unclear math and no system.
In this guide, you will learn how saving for our dream house becomes simple when you break it into clear numbers, realistic timelines, and a weekly system you can actually follow. No fluff. Just a practical roadmap.
Why Saving for Our Dream House Feels So Hard
Most families make three common mistakes:
- They only think about the down payment savings
- They do not calculate total house related costs
- They try to “save what is left” instead of planning first
Saving for our dream house is stressful because the goal is emotional. It is not just a purchase. It is security, pride, stability, and a future.
But emotions do not replace math.
Once you turn the dream into numbers, the stress drops dramatically.
Step 1: Calculate Your Real House Savings Target
Saving for our dream house includes more than a down payment.
Your complete target should include:
- Down payment savings
- Closing costs
- Moving expenses
- Initial repairs or furniture
- A safety cushion after purchase
If you only save for the down payment, you will feel behind the moment extra costs appear.
Simple Formula
Total House Fund Needed = Down Payment + Closing Costs + Moving + Cushion
Now subtract what you already have saved.
That is your real target.
Step 2: Turn the Big Number Into a Monthly Goal
Saving for our dream house becomes manageable when you break it into months.
Monthly Savings Goal = (Remaining Target) ÷ (Months Until Purchase)
Example:
- Total target: 60,000
- Already saved: 10,000
- Remaining: 50,000
- Timeline: 25 months
Monthly goal = 2,000
Now it is no longer “a huge dream.” It is a clear monthly commitment.
Step 3: Build a Monthly Budget Plan That Supports the Goal
If you are serious about saving for our dream house, your budget must reflect it.
Structure your monthly budget like this:
1. Fixed Expenses
- Rent
- Insurance
- Loan payments
2. Variable Essentials
- Groceries
- Utilities
- Transportation
3. Flexible Spending
- Dining out
- Shopping
- Entertainment
4. House Savings Contribution (Non Negotiable)
Your house savings plan should come before lifestyle spending, not after.
Step 4: Track Spending Without Overcomplicating It
You cannot improve what you do not measure.
Saving for our dream house requires visibility.
Focus on these common “budget leaks”:
- Food delivery creep
- Subscription renewals
- Impulse shopping
- Convenience spending
- Unplanned events
Even small adjustments can free up hundreds each month.
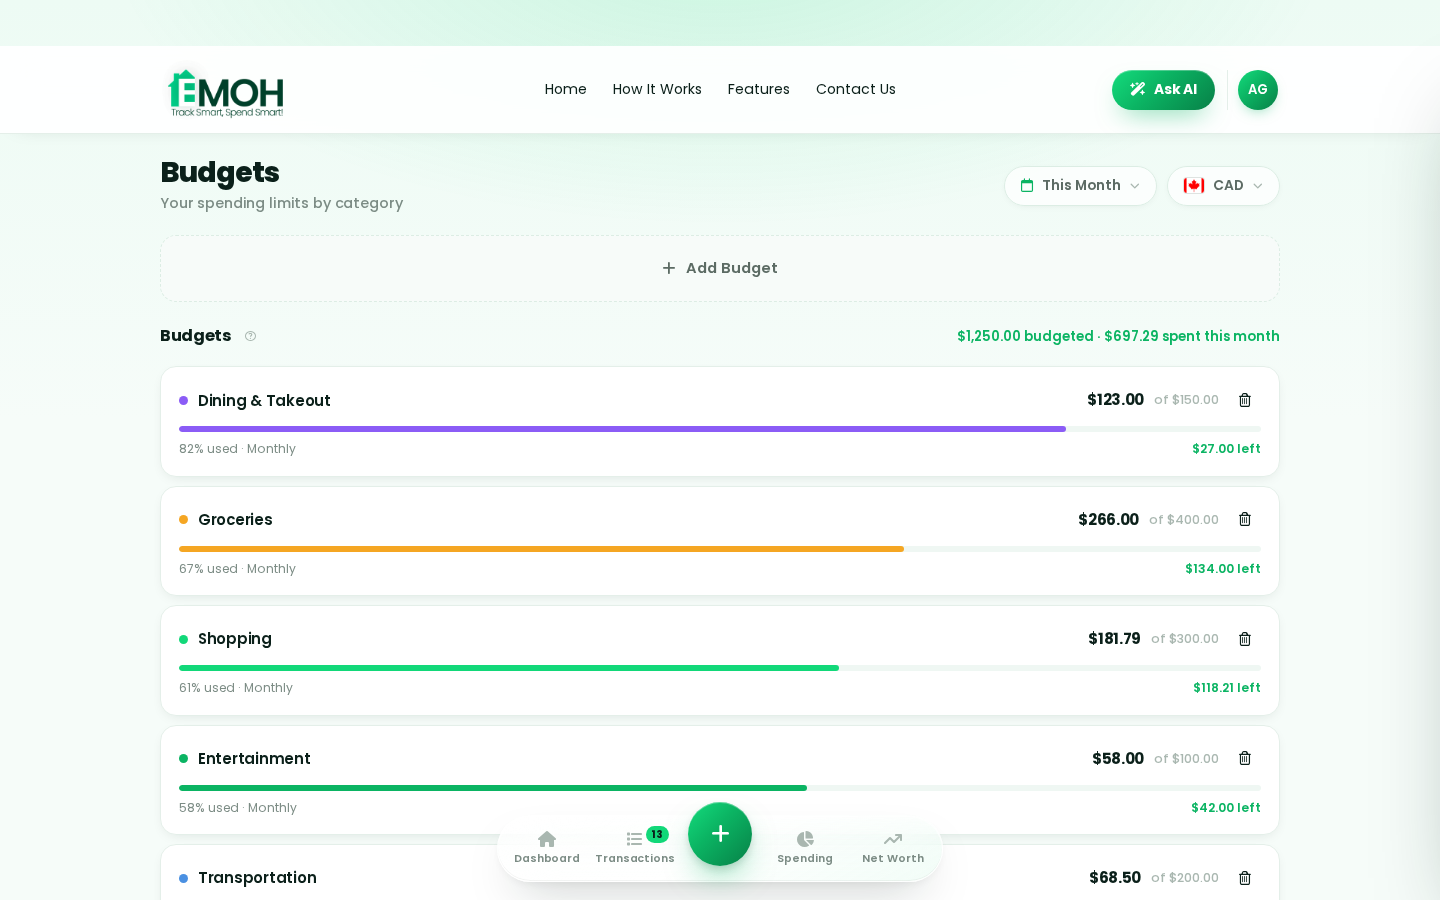
This is where structured category budgeting helps. Platforms like EMOH Pay are designed to simplify expense tracking, savings goals, and monthly budget planning in one place so households can clearly see where money is going without juggling spreadsheets.
Clarity reduces stress.
Step 5: Automate Your Down Payment Savings
Automation removes emotion from the process.
Set up automatic transfers right after payday. Treat your house fund like a bill you owe your future.
When saving for our dream house becomes automatic, consistency improves instantly.
Step 6: Increase Savings Without Feeling Miserable
You do not need extreme sacrifices. You need focused adjustments.
High impact strategies:
- Save a percentage of bonuses and tax refunds
- Temporarily reduce one lifestyle category
- Pause non essential subscriptions
- Direct side income straight to the house fund
- Negotiate recurring bills
Short term discipline creates long term stability.
Step 7: Protect Your Emergency Fund
One major mistake people make while saving for our dream house is draining their emergency savings.
Never use your entire financial cushion for a down payment.
A home brings new responsibilities:
- Repairs
- Maintenance
- Insurance adjustments
Security first. Always.
Saving for Our Dream House as a Couple
Money stress often comes from misalignment.
If you are saving for our dream house with a partner:
- Agree on one clear target
- Set a shared timeline
- Review progress weekly
- Assign budget categories to each person
Shared goals reduce conflict.
When both partners can see progress clearly through a budgeting system, motivation increases and arguments decrease.
Where Should You Keep Your House Savings?
If your timeline is short, prioritize safety and accessibility.
Options many people consider:
- High yield savings accounts
- Dedicated house savings accounts
- Separate digital savings buckets
Avoid high volatility investments if you plan to buy soon.
Protect the dream from unnecessary risk.
Common Mistakes That Delay Homeownership
- Waiting to “start later”
- Not tracking expenses
- Underestimating closing costs
- Ignoring small daily spending
- Changing the goal every few months
Saving for our dream house requires consistency, not perfection.
What Changes Everything
The biggest mindset shift is this:
Stop saying “We cannot afford it.” Start asking “What system would make this possible?”
When you:
- Know your exact number
- Follow a structured monthly budget
- Automate savings
- Track spending weekly
Saving for our dream house becomes predictable instead of stressful.
Frequently Asked Questions
How much should we save for a dream house?
It depends on the home price, loan type, and location. At minimum, plan for a down payment, closing costs, moving expenses, and a financial cushion.
Is 20 percent down required?
No. Many loan programs allow lower down payments. However, higher down payments can reduce monthly costs and eliminate mortgage insurance.
How long does saving for our dream house take?
It depends on income, home prices, and savings rate. A clear monthly savings plan shortens the timeline significantly.
What is the best way to save for a down payment?
Automate transfers, reduce budget leaks, increase income if possible, and track spending consistently.
Should we invest our house savings?
If you plan to buy within a few years, prioritize stability over growth. Volatility can delay your purchase.
How do couples avoid money arguments while saving?
Set shared goals, track expenses transparently, review progress weekly, and use a budgeting system that both can access.
What if our monthly goal feels too high?
Adjust one of three levers:
- Extend timeline
- Increase income
- Lower purchase price range
Do we need a budgeting app?
You need a clear system. Whether it is a spreadsheet or a structured budgeting platform, clarity and consistency matter most.
Final Thoughts
Saving for our dream house sounded stressful at first.
But once we calculated the real target, built a realistic monthly budget plan, automated savings, and tracked expenses clearly, everything changed.
The dream did not shrink.
The system improved.
If you want a structured way to track spending, manage savings goals, and stay aligned as a household, you can explore tools designed for this purpose like EMOH Pay at: https://emohpay.com/ .
Also download the EMOH Pay app from Google Play and App Store .
Clarity creates confidence. Confidence builds homes.
Try the savings goal calculator
Reading is step one — EMOH Pay makes it automatic. Free to start on phone and web.
Open it➜What should you know about everyday budgeting?
Everyday budgeting comes down to three habits: know what comes in, decide where it goes, and check in daily. EMOH Pay makes all three effortless — free expense tracking and budgets on phone and web, a Daily Money Digest each morning, and bank-grade AES-256 security throughout.
Everyday budgeting: the essentials
Money works better as a team sport — shared live numbers end the guesswork and the arguments.
Five minutes a week with a daily digest beats a perfect spreadsheet you abandon in February.
You can start everyday budgeting today at $0 — no card required, on iPhone, Android or the web.
Auto-categorization, recurring bills and bank sync take the admin out of the habit.
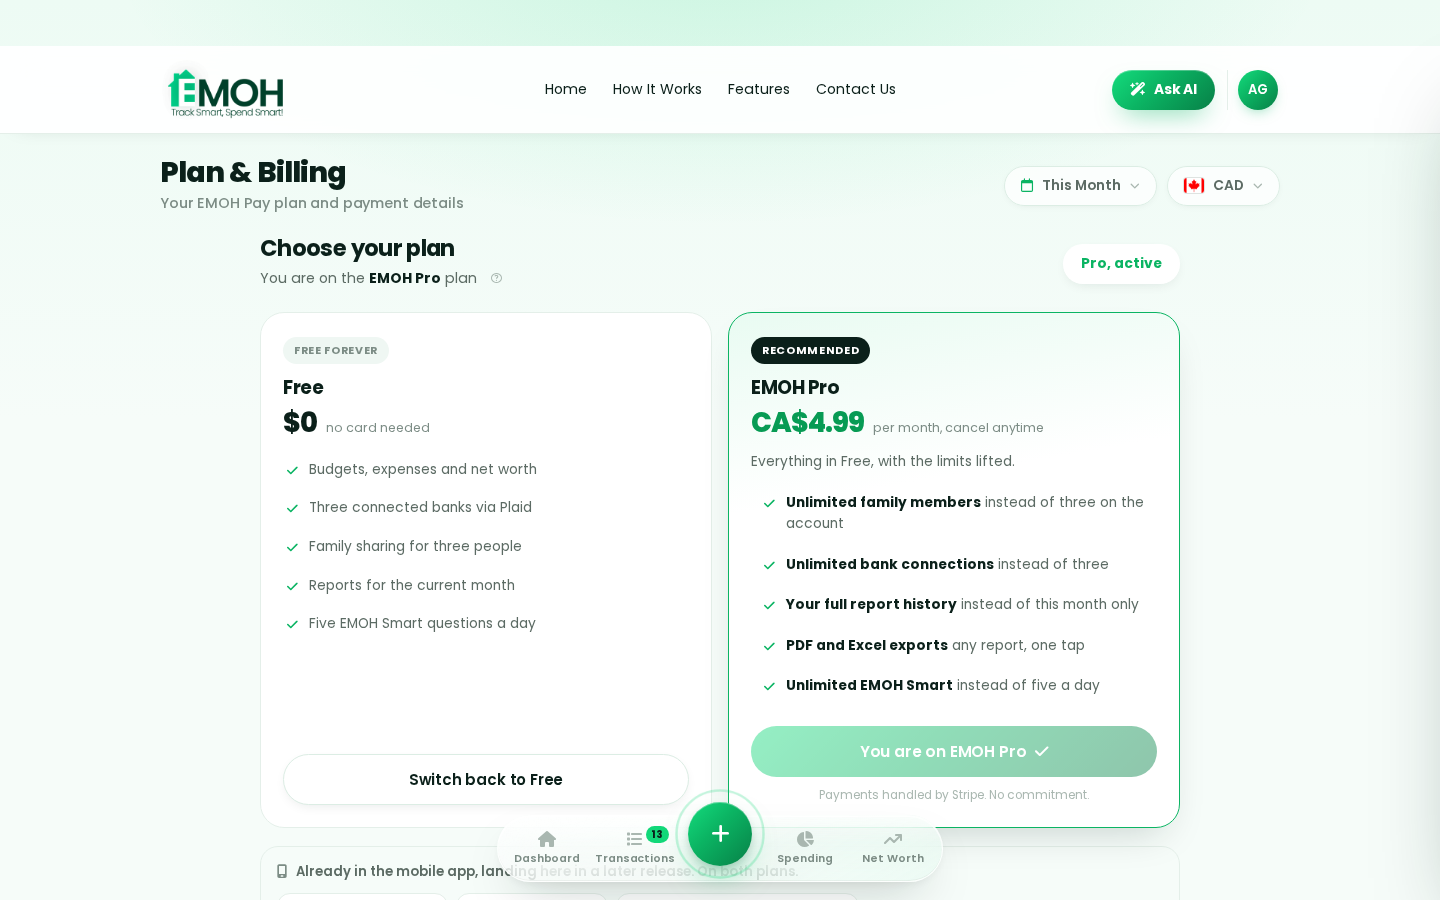
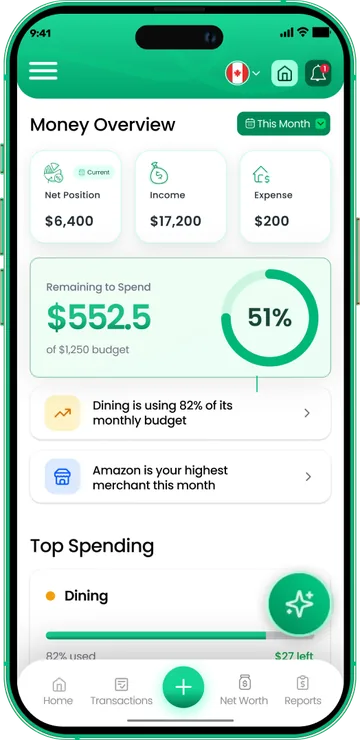
One app for everyday budgeting — on every screen.
Track on your phone in the checkout line, review on the web app at your desk. EMOH Pay keeps everyday budgeting in sync the second anything changes, so the numbers you act on are always current.
Start free on the web➜ Explore all features➜Real spending, really tracked
From the morning coffee to the monthly rent — Canadians log, tag and learn from every expense on EMOH Pay.
Everything you need for everyday budgeting
Track Smart, Spend Smart! The complete toolkit, free to start:
Ask questions about your own spending in plain language and get instant answers.
Assets minus debts, always current — watch the number that actually measures progress.
Log any expense in two taps — or let bank sync do it automatically. Every dollar gets a category.
Vacations, emergencies, down payments — set the target and watch it fill.
One calm summary every morning: what you spent, what's left, what needs attention.
Everyone sees the same live numbers, each with their own login. Free forever.
How to start everyday budgeting with EMOH Pay
Four small steps, five minutes total:
EMOH Pay vs. the usual ways to handle everyday budgeting
| EMOH Pay | Spreadsheet | Typical budgeting app | |
|---|---|---|---|
| Free tier | Free forever | Free | Limited trial |
| Paid tier | EMOH Pro — $4.99/mo | — | $10–15/mo |
| Expense tracking | ✔ Two taps or automatic | Manual entry | ✔ |
| Budgets & overspend alerts | ✔ Built in | ✖ None | Varies |
| Net worth tracking | ✔ Live | Formula gymnastics | Often paid add-on |
| Phone + web sync | ✔ Instant | ✖ Manual | Varies |
| Family sharing | ✔ Free | ✖ Shared-file chaos | Often paid add-on |
| GST/HST tracking | ✔ Automatic | ✖ Formula gymnastics | ✖ Rare |
| 148 currencies | ✔ Automatic conversion | ✖ None | Limited |
| Ask AI | ✔ Included | ✖ None | ✖ Rare |
| Daily Money Digest | ✔ Built in | ✖ None | Push spam |
| PDF & Excel exports | ✔ One tap | ✔ Manual | Varies |
| Bank sync (Canada) | ✔ Plaid, read-only (Pro) | ✖ None | US-first, patchy |
Everything above is free to start — and the full EMOH Pro upgrade is just $4.99/month, a third of what typical budgeting apps charge.
Real everyday budgeting problems we actually solve
Everyday budgeting that fits real life
Money habits only stick when they fit the life you already live. EMOH Pay was built for the checkout line, the kitchen-table conversation and the Sunday five-minute review — not for accountants. Two taps to log an expense, one glance to know where you stand.
Get started free➜ See how it works➜Your money data, protected like a bank's
The same encryption standard banks use, protecting your data at rest and in transit.
Bank connections run through Plaid and can only read transactions — never move money.
Built in Canada to Canadian privacy law. Your data is yours — never sold, ever.
Everyday budgeting — frequently asked questions
Is EMOH Pay free for everyday budgeting?
Yes — EMOH Pay is free to start on iPhone, Android and the web. Budgeting, expense tracking and net worth are all included, which covers everything you need for everyday budgeting. EMOH Pro adds bank sync via Plaid and advanced AI for just $4.99/month.
Is my financial data safe with EMOH Pay?
Yes. EMOH Pay uses AES-256 encryption, bank connections are read-only through Plaid, and the app is built to Canadian PIPEDA privacy standards. Your data is never sold.
Can I share my budget with my family?
Yes — Family Account Sharing is included free. Each member gets their own login while budgets and expenses stay shared in real time, which makes everyday budgeting a team effort instead of a solo chore.
What is the best way to get started with everyday budgeting?
Start simple: create a free EMOH Pay account, enter your income and accounts, then set budgets for your top three spending categories. Most people are fully set up in about five minutes, and the Daily Money Digest keeps the habit going.
Do I need to connect my bank account?
No. Manual tracking is free forever and takes two taps per expense. If you want automatic imports, EMOH Pro connects Canadian banks securely through Plaid with read-only access.
Does EMOH Pay work on both phone and computer?
Yes. EMOH Pay has full apps for iPhone and Android plus a complete web app, and everything syncs instantly. Phone in your pocket, web app at your desk — the same live numbers everywhere.
More from EMOH Pay
Start free today
Free on iPhone, Android and the web. Upgrade to EMOH Pro anytime for bank sync and advanced AI.
Download for iOS➜ Get it on Android➜